
Build & Fix Credit - Dovly AI
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
Build & Fix Credit - Dovly AI - Screenshots
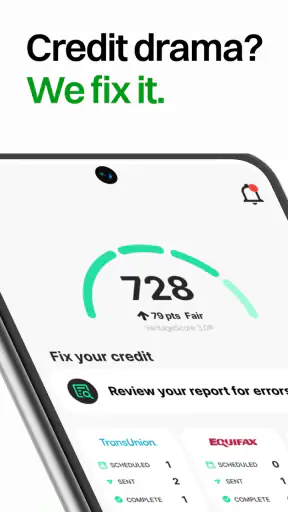
Pros
- AI-guided credit improvement plan is simple for beginners.
- Credit monitoring can help users spot changes more quickly.
- Automated dispute support may save time on eligible credit issues.
- Progress tracking makes credit-building goals easier to follow.
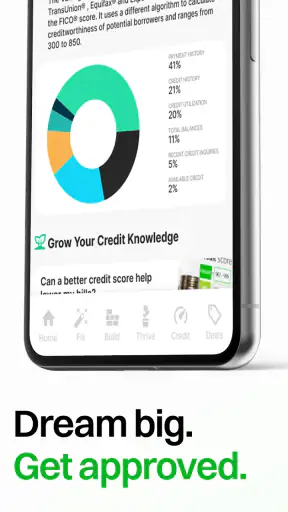
- Educational guidance explains credit factors in accessible language.
Cons
- Some useful features may require a paid subscription.
- Results depend on bureau updates and cannot be guaranteed.
- Disputes may take time and do not always change credit reports.
- Users must share sensitive financial and personal information.
- The app may not support every credit bureau or reporting issue.
Build & Fix Credit - Dovly AI - Description
- App Name
- Build & Fix Credit - Dovly AI
- Package Name
- com.dovly.app
- Developer
- Dovly.com
- Category
- Finance
- Last Updated
- Apr 25, 2022
- Version
- 9.5.0
Improving your credit can feel unnecessarily complicated, especially when you are not sure which action matters first. Build & Fix Credit - Dovly AI is designed to make that starting point less intimidating. I found it most useful as a guided finance app for people who want to understand their credit journey and take organized steps instead of jumping between scattered advice, credit reports, and unfamiliar terminology.
The app is developed by Dovly.com and is available as a free finance app for everyone. It has built a sizeable audience, with more than a million installs and a 4.7 average from roughly 83 thousand ratings. Those figures do not replace personal judgment, but they do suggest that the app has become a familiar entry point for people looking for help with credit building and credit repair.
My main advice is to approach it as a credit-management companion, not as a magic switch that instantly changes a score. The most valuable experience comes from using it consistently, reading what each suggested action means, and treating any progress as part of a longer financial routine.
What to expect before you begin
The app’s central idea is to bring credit-related guidance into one place with an AI-focused experience. In practical terms, that means the first session is less about browsing a large collection of financial articles and more about getting oriented around your own credit goals. If you are completely new to credit, that guided approach can be less overwhelming than trying to decode every part of a credit report alone.
I would describe the tone as beginner-friendly, but the subject itself still requires patience. Credit improvement depends on information, timing, account behavior, and follow-through. An app can help you notice problems and organize your next move; it cannot make a lender approve an application or guarantee a particular score outcome. That distinction is important because unrealistic expectations are one of the easiest ways to become frustrated with any credit service.
The “all credit, no karma” positioning points toward a focused experience rather than a general personal-finance dashboard. You are not opening it primarily to track groceries, build a household budget, or manage investments. It is better suited to someone whose immediate concern is understanding credit and making a plan around it.
There is also a paid layer to keep in mind. The app itself is free to install, while in-app purchases range from under a dollar to nearly two hundred dollars per item. I recommend paying attention to every screen that explains an optional purchase and deciding whether it solves a problem you actually have. A free starting point is useful, but “free” does not mean every available service inside the app has no cost.
The app is rated for Everyone, which makes it approachable for a broad audience. Still, credit decisions are personal and sometimes serious. If you are dealing with identity theft, legal disputes, bankruptcy, collections, or a lender deadline, I would not rely on an app alone. Use it for organization and education while getting appropriate help for issues that require professional or official attention.
Who will get the most from it
I think it is a strong fit for a first-time credit user, someone rebuilding after missed payments, or a person who keeps postponing credit maintenance because the process feels confusing. It can also help users who have looked at a score but have no idea what to do next. The value is not only in opening the app; it is in turning a vague goal such as “fix my credit” into a sequence of manageable checks and actions.
It is less suitable for someone who wants a complete budgeting platform, a bank account, or a broad financial planning tool. It is also not the right choice for a user who expects immediate score changes after one tap. If you already have a detailed system for monitoring reports, disputing errors, and tracking account utilization, the app may feel more like an additional guide than a replacement for your existing process.
Starting carefully and finding your first useful action
Make the first setup a review, not a race
When I start an app in a sensitive category such as finance, I prefer to slow down during setup. Read each prompt, check that the information you enter is correct, and avoid tapping through screens simply to reach the dashboard. Credit-related recommendations are only as useful as the context behind them, so a rushed setup can lead to a confusing first impression.
Keep your goal simple at the beginning. You might want to understand why your credit is not where you want it, repair information that looks wrong, or establish healthier habits before applying for something important. Choosing one immediate goal makes the app easier to evaluate than trying to solve your entire financial history in one session.
A practical first-session habit is to keep a note outside the app with three items: what you already know, what looks unclear, and what you want to verify. For example, you may know that a payment was made but not understand how an account is being reported. That distinction prevents you from treating every unfamiliar entry as an error.
Another useful precaution is to distinguish between a recommendation and a completed action. A prompt may tell you where attention is needed, but you may still need to review details, gather documents, contact the relevant company, or follow an official process. I would never assume that tapping a task inside a credit app automatically settles an issue with a lender or reporting agency.
Turn the first session into a concrete win
For a new user, the first meaningful success should be something you can verify, not simply the feeling that the app looks polished. A good first win might be identifying one account or habit that deserves attention, writing down a clear next step, or understanding a term that previously made your report difficult to read.
Here is the everyday scenario I found most realistic. Imagine you are preparing to rent a new apartment and realize that your credit history needs attention. Instead of opening several unrelated services, you use Dovly AI to organize your starting point. You review the guidance, identify the most urgent issue, and create a small checklist: confirm the account details, collect supporting records, and decide which official contact should handle the question. The app has not promised you an apartment, but it has helped turn anxiety into an orderly process.
That kind of progress is easy to underestimate. Credit work often involves waiting, checking, and repeating rather than dramatic changes. I recommend taking a screenshot or keeping a personal note of what you reviewed and when. This gives you a reference point and helps you avoid reopening the same issue without learning anything new.
One non-obvious trade-off is that automation can make the first step feel easier while also encouraging passive behavior. If the app presents a recommendation, ask yourself why it matters and what evidence supports it. The more you understand the reason behind an action, the less likely you are to follow a generic suggestion that does not fit your circumstances.
Where first-time users may become confused
Credit language is full of terms that sound similar but describe different things. A credit score is not the same as a credit report, and a report entry is not automatically proof that something is inaccurate. Likewise, an item that hurts your profile may be legitimate and may require a different response from an item that contains incorrect information.
This is where I would use the app as a learning aid rather than a final authority. When a recommendation appears, separate it into three questions: what is being identified, why might it matter, and what action is actually available to me? If you cannot answer the third question, do not rush into a paid option or contact a company without first gathering more context.
Users can also become confused by the difference between monitoring and improvement. Seeing information about your credit does not itself repair it. A useful routine is to review the app, write down one action, complete that action through the appropriate channel, and then return later to check your records. That workflow is slower than expecting an instant result, but it is much more realistic.
Another point worth remembering is that credit changes may not appear immediately. Even when you do everything correctly, reporting cycles and account updates can take time. I would judge the app by whether it helps me understand and manage the process, not by whether my score moves after a single visit.
How it compares with usual alternatives
The usual alternative is to manage credit directly through reports, lender websites, creditor support channels, and personal notes. That approach can be more authoritative for resolving a specific issue because you are working with the source of the account information. Its weakness is that it can be difficult to organize, especially for someone who does not know which issue deserves attention first.
Another alternative is a general credit-monitoring service. Those tools may be useful for alerts and regular visibility, but they are not always built around a guided credit-building journey. Dovly AI’s appeal is the more focused path: it tries to help users move from uncertainty toward an action plan rather than simply presenting another number to watch.
On the other hand, a direct approach may be better if your situation is already clear. If you know that a payment was missed, the most effective next step may be contacting the creditor and arranging a solution rather than spending time exploring an app. If you are disputing a serious error, official documentation and careful records matter more than a convenient interface.
The trade-off is therefore straightforward. This app can reduce confusion and improve organization, while direct financial channels remain essential for verification and resolution. I would use both when necessary instead of expecting one product to replace the entire credit system.
Using the app without losing control of your plan
My preferred routine is short and repeatable. Open the app when you have enough time to read, review the current guidance, choose one priority, and record what you intend to do next. Avoid turning every notification or new suggestion into an urgent task. Credit improvement is easier to sustain when the plan is realistic.
It is also worth reviewing the cost of any optional service before continuing. Since purchases can range from $0.99 to $199.99 per item, the difference between a small convenience and a significant expense is substantial. I would compare the explanation of the paid feature with the action you are trying to complete and ask whether the same step can be handled directly through an official, no-cost channel.
The current version is 9.5.0, and the app supports devices running Android 7.0 or later. That makes it accessible to many older Android phones, though your personal experience can still depend on the device and operating system you use. Keeping the app updated is sensible for a finance tool, but I would still read changes to features or purchase screens rather than assuming the experience stays identical forever.
Privacy should be part of your decision-making too. Credit information is sensitive, so I would review the app’s own explanations during setup and use a password you do not reuse elsewhere. I would also avoid entering information on a shared device and would sign out or secure the phone if other people can access it. These are small habits, but they matter more when an app relates to financial identity.
The next step after the first visit
After the first useful session, do not measure success by how many screens you explored. Measure it by whether you can explain your next action in plain language. “I need to check this account detail and gather my records” is a useful outcome. “I should improve my credit somehow” is still too vague.
Once you have one priority, give yourself a reasonable review point. Return to see whether the information has changed, whether you completed the task, or whether a different issue now deserves attention. Keep your own records because an app dashboard is not a substitute for documentation, especially if you are communicating with a creditor or handling a dispute.
I also recommend using the app alongside basic habits that do not depend on any single service: make payments on time, avoid applying for credit impulsively, check account details carefully, and keep track of commitments you can realistically afford. Dovly AI can help make those habits easier to organize, but it cannot make an unaffordable decision safe.
For someone starting from zero, the reassuring part is that you do not need to understand every credit concept before opening the app. Begin with one question, read the guidance, and verify the action before committing to it. That is a much better path than chasing quick fixes or paying for something simply because the wording sounds urgent.
My final view is positive but measured. Build & Fix Credit - Dovly AI is a useful starting point for people who want a clearer route into credit building and repair, particularly those who feel stuck between a score and a long list of unfamiliar details. Its free entry point, approachable focus, and AI-led guidance make it easy to try, while the optional purchases and the limits of automated advice deserve careful attention.
I would recommend it to a first-time user who wants structure and is willing to remain involved in the process. I would not recommend treating it as a guarantee, a replacement for official financial channels, or a complete money-management app. Used thoughtfully, it can help you find the first meaningful action and keep your credit work organized. That is not an instant fix, but for many people, having a clear and manageable starting point is exactly what makes improvement possible.
FAQ
What is Build & Fix Credit - Dovly AI?
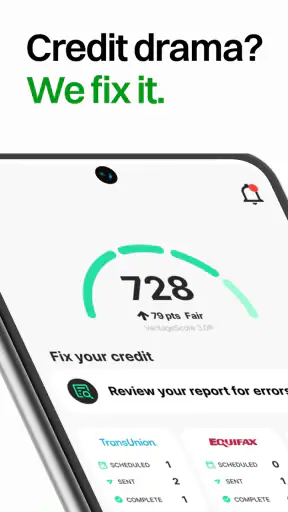
Build & Fix Credit - Dovly AI is a credit-management app designed to help users monitor and improve their credit profile. It combines credit insights, personalized recommendations, dispute-related guidance, and credit-building tools in one place. After reviewing the app, its main appeal is the straightforward dashboard, which presents credit information and suggested actions in a way that is easier to understand than many traditional financial services.
How does Dovly AI help improve my credit score?
The app can help you identify possible issues affecting your credit and organize steps that may support healthier credit habits. Depending on your plan and eligibility, features may include credit monitoring, personalized recommendations, and assistance with challenging potentially inaccurate information. However, Dovly cannot guarantee a specific score increase. Results depend on the accuracy of your credit reports, your payment history, debt levels, and the actions you take over time.
Is Build & Fix Credit - Dovly AI free to use?
Dovly offers access to some credit-related tools at no cost, but certain features may require a paid membership or upgraded plan. Before downloading or subscribing, users should carefully review the current pricing, billing frequency, trial conditions, and cancellation policy shown in the app or app store listing. A subscription may renew automatically, so it is important to manage it through the appropriate Google Play or Apple account settings.
Is my personal and financial information safe in the app?
Because credit services require sensitive personal information, privacy and security should be considered before creating an account. Dovly may request details needed to verify your identity, connect credit information, or provide its services. Review the company’s privacy policy, permissions, data-sharing practices, and security explanations before proceeding. You should also use a strong, unique password and avoid accessing your account on unsecured public networks.
Can Dovly remove negative items from my credit report?
Dovly may help users review credit-report information and address items they believe are inaccurate, incomplete, or unverifiable, but it cannot legally remove accurate negative information simply because it lowers a score. Credit-report disputes generally require supporting details and may take time to process. Users should check reports from the major credit bureaus, keep copies of submitted documentation, and remember that credit improvement is usually gradual rather than immediate.


